
Not Every Expense is a Cost
Accurate Classification of Expense Items
Misclassified expenses distort both reports and taxes at the end of the period. We explained frequently confused items and the correct distinction.
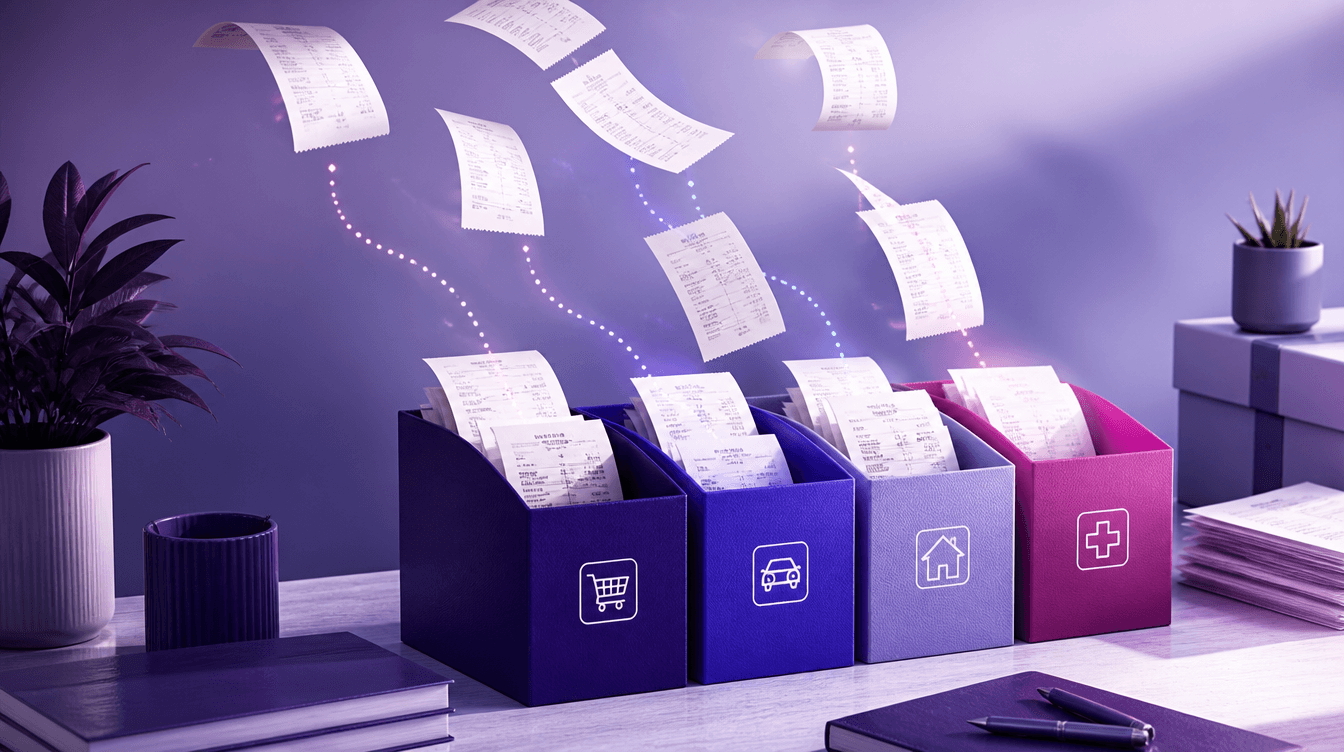
If every outgoing payment from the cash register is recorded as an "expense," the profit statement at the end of the period will lie. Misclassification distorts both pricing decisions and the tax base.
In a small business, the real issue isn't a complex chart of accounts; it's confusing four or five basic distinctions. In this article, we break down frequently confused items in practical language.
First, the four big boxes
| Box | What it means | Example |
|---|---|---|
| Direct cost | Purchases tied to a product/service | Purchase invoice of goods to be sold |
| General expense | Periodic spending that keeps the business running | Rent, electricity, software subscription |
| Investment / fixed asset | An asset that doesn't get used up all at once, spanning multiple periods | Computer, machinery, fixture |
| Non-deductible expense (NDEP) | Spent, but cannot be deducted from the tax base | Personal spending, fines (depending on circumstances) |
Placing the same amount in a different box changes the phrase "our profit this month is this." That is why classification is not an accounting subtlety, but the foundation of management decisions.
The five most commonly confused situations
- Recording inventory purchases as general expenses. If goods are bought but not sold, this is not a period expense; it is inventory. It turns into a cost when sold.
- Recording fixed assets as expenses. A laptop or machinery is not a "monthly expense"; it goes through asset registration + depreciation logic.
- Counting partner/personal spending as a business expense. If it has nothing to do with the business, it goes to NDEP or the partner current account receivables/payables.
- Recording advances and deposits as expenses. Money going out doesn't automatically mean an expense; it can remain as a receivable/collateral until offset.
- Throwing shipping and commissions into "others." In e-commerce, these items determine profitability; if not tracked separately, product-based decisions become flawed.
In our article on product costing, we also covered how direct costs are reflected in pricing.
A practical classification routine
Ask three questions for every expense:
- Which product or service is this expense tied to? If it is tied, it leans toward a direct cost.
- Does its benefit end this month, or will it last a long time? If it lasts long, the likelihood of an investment/fixed asset is high.
- Is it acceptable from a tax perspective? If there is no receipt or if it is personal, there is an NDEP risk.
Keep category names in your pre-accounting few and consistent. If "others / miscellaneous" is swelling, it means the classification isn't working.
The typical chain that ruins the report
You bought goods → recorded them as an expense instead of inventory → profit looked low that month → you raised the price → the next month, when the inventory was sold, profit surged. In reality, the business was the same; the entry was wrong.
The same chain happens with fixed assets: writing off a large purchase as an expense in a single month results in a loss that month, followed by fake "improvements" in subsequent months. Don't fall into this illusion when making decisions.
Frequently asked questions
Can I expense low-value fixed assets?
Legislation may have practical applications for low-value fixed assets; amounts and practices change periodically. Ask your financial advisor for the threshold; don't expense things on your own just because they are "small."
Does an NDEP entry also disrupt cash flow?
The cash outflow may be real. The NDEP distinction is for the tax base. Cash has left the business in the cash plan; but it is processed differently on the profit/loss and tax side.
Is it a problem to change the category later?
It is easy to fix before the period closes. For periods where tax returns have already been filed, corrections enter the financial advisor's workflow. That's why putting it in the right box during the month is cheaper.
Does receipt scanning automatically solve classification?
It can read the amount and offer suggestions; the final category decision remains up to you. Especially the distinction between inventory / fixed assets / personal spending requires human approval.
In summary: not every expense is an expense. The right box means the right profit and the right decision.
By opening a free account on Qolay.App, you can track your expenses by category and match them with cash and bank transactions.
This article is for general informational purposes only. Expense acceptance conditions, NDEPs, and fixed asset practices vary periodically and by file; consult your financial advisor for your specific situation.
Related articles
Other guides close to this topic.
Sole Proprietorship or Limited Liability Company?
Tax Burden Is Not the Only Criterion
Choosing between the two structures isn't just about the tax rate. We compared liability, costs, and growth scenarios side by side.
How to Process Personnel Expenses in Pre-Accounting?
Salary, Bonus, and Advances Separately
Salary payments are not a single line. We explained how net payments, SSI contributions, and advance deductions are recorded separately and how they match with cash and bank accounts.
Shipping Expense and Return Management
Returns Quietly Eat Profit
Profit calculations for a high-return product remain only on paper. We explained how to track shipping and return costs.